S&P500 Daily Action Areas & Price Targets 24/9/26
S&P500 Daily Action Areas & Price Targets 24/9/26
***QUOTING ES1!(Z CONTRACT LEVLES) FOR CASH US500 EQUIVALENT LEVELS, SUBTRACT POINT DIFFERENCE***
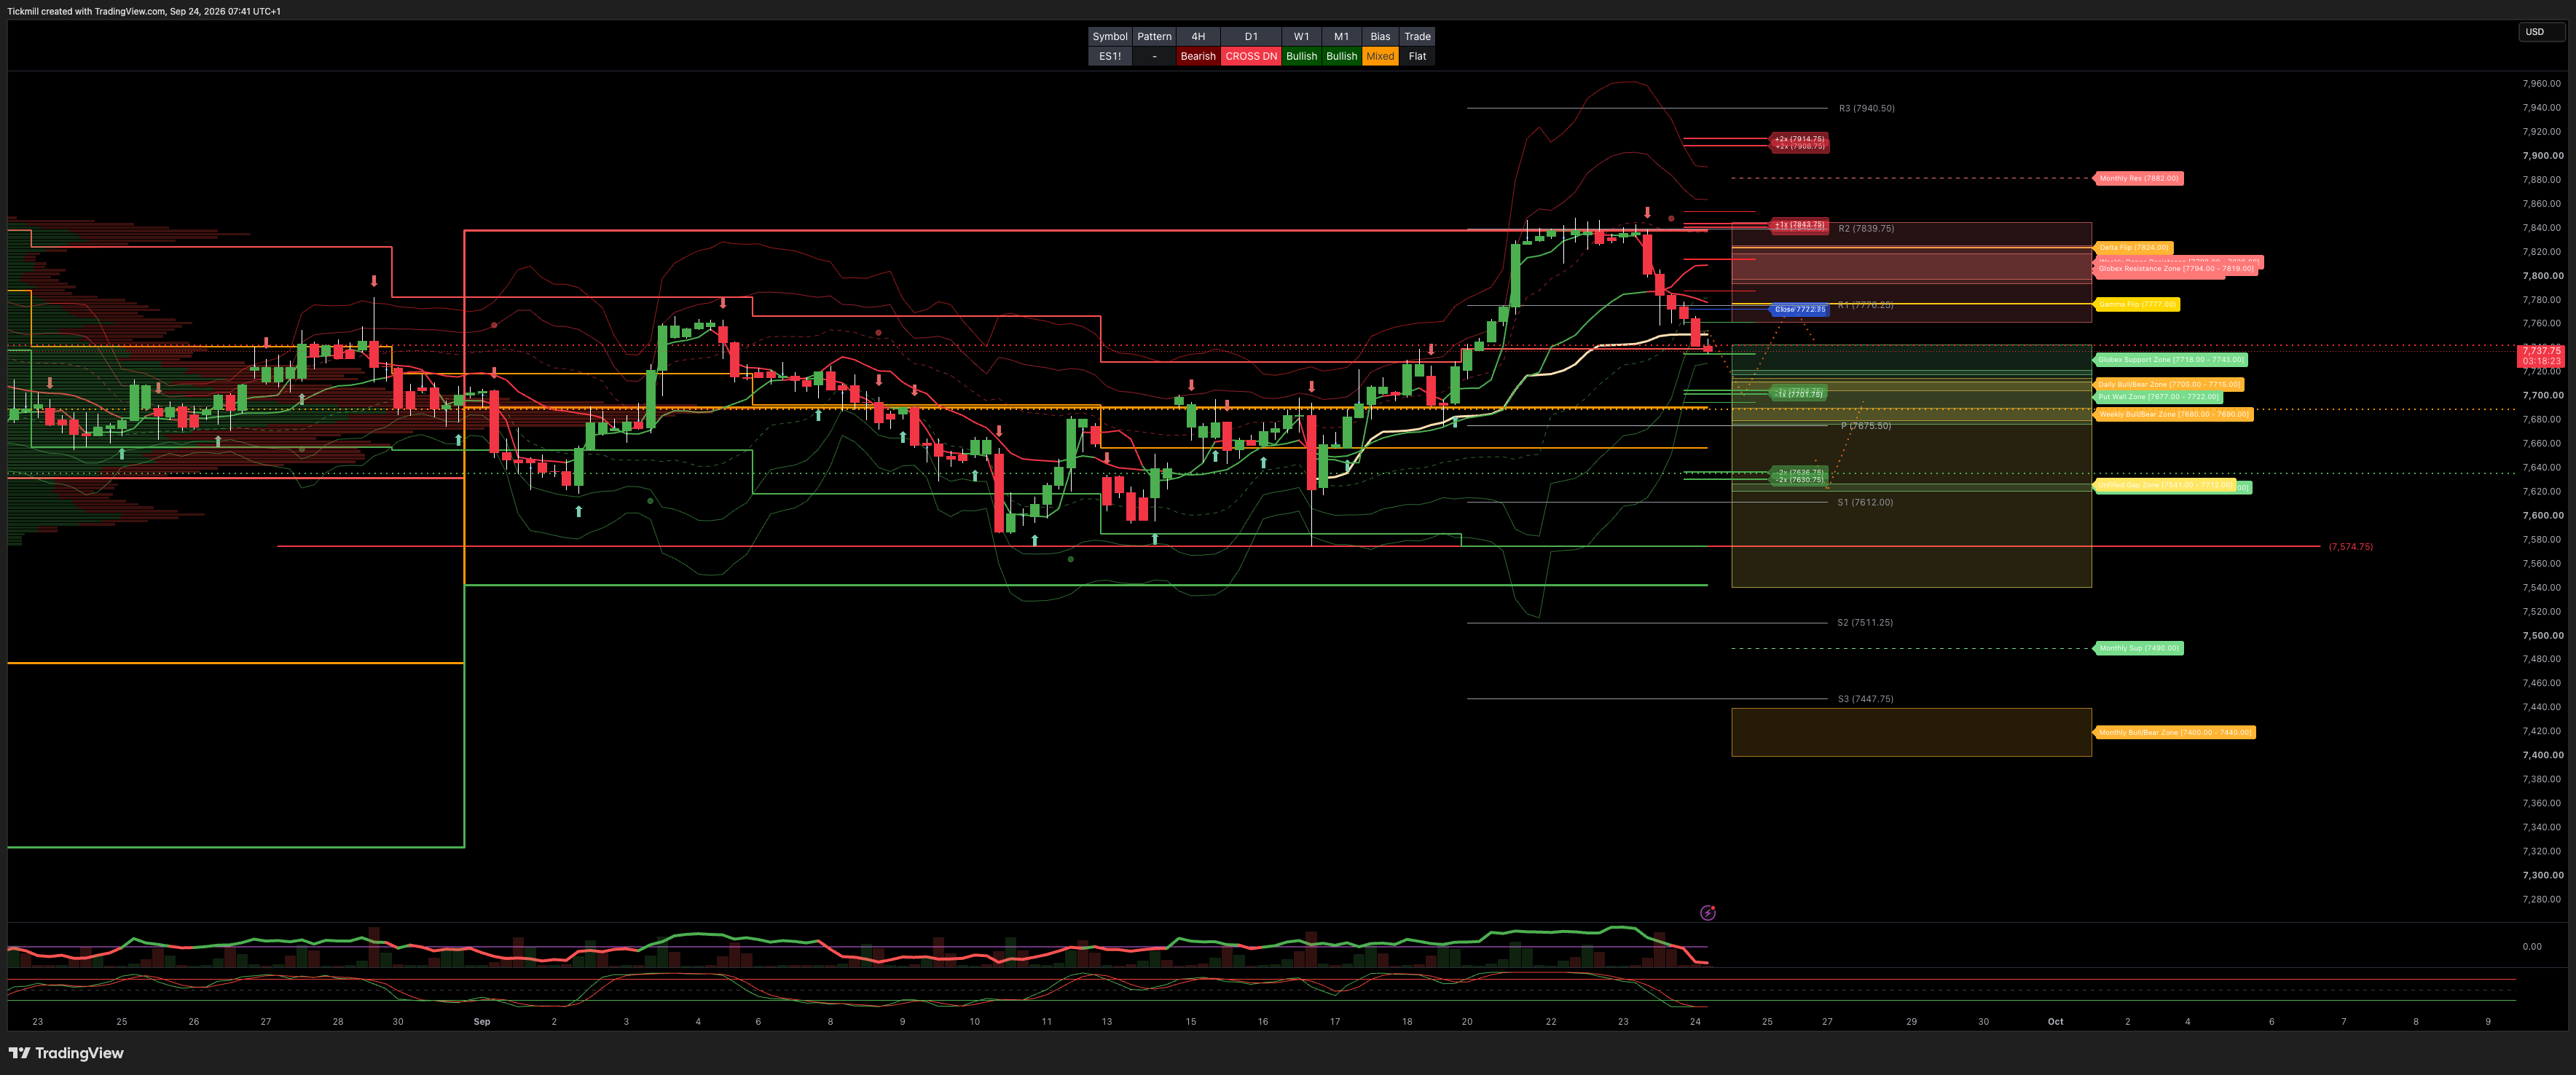
MONTHLY-WEEKLY& DAILY LEVELS
MONTHLY BULL BEAR ZONE 7440/7400
MONTHLY RANGE RES 7882 SUP 7490
WEEKLY BULL BEAR ZONE 7690/80
WEEKLY RANGE RES 7826/7798 SUP 7621/27
DAILY BULL BEAR ZONE 7705/15
GLOBEX RANGE RES 7794/7819 SUP 7743/18
GAMMA FLIP 7777
DELTA FLIP 7824
CALL WALLS 7845/7762
PUT WALLS 7722/7677
UNFILLED GAPS 7541 - 7712
DAILY STRUCTURE - BALANCE - 7758.7848
WEEKLY STRUCTURE - OTFL - 7717
MONTHLY STRUCTURE - OTFH - 7542
VIX BULL BEAR ZONE 17.7
VVIX / VIX 5.84 sits comfortably inside the historical median range (typically 5.0 to 6.0), indicating a stable options pricing environment without acute stress
PRIMARY TRADES & TARGETS
LONG ON REJECT/RECLAIM DBBZ TARGET DAILY RANGE RES
***ADDITIONAL SETUPS & TARGETS HIGHLIGHTED ON THE CHARTS***
(I FADE TESTS OF 2 SIGMA LEVELS ESPECIALLY INTO THE FINAL HOUR OF THE NY CASH SESSION AS 90% OF THE TIME WHEN TESTED THE MARKET WILL CLOSE ABOVE OR BELOW THESE LEVELS)
SPX PUT/CALL RATIO 1.18 (The numbers reflect options traded during the current session.) A put-call ratio below 0.7 is generally considered bullish, and a put-call ratio above 1.0 is generally considered bearish.
JHEQX Q3 Collar Short Call Cap: ~7,750 – 7,900 - Long Put Strike: ~7,050 – 7,100 (approx. 5% downside protection) Short Put Strike: ~5,950
DEC2025 OPEX to DEC2026 OPEX is 945 points giving us a range of [5889,7779]
Notes On Structure Implications
Balance: This refers to a market condition where prices move within a defined range, reflecting uncertainty as participants await further market-generated information. Our approach to balance includes favouring fade trades at the range extremes (highs/lows) while preparing for potential breakout scenarios if the balance shifts.
One-Time Framing Higher (OTFH): This represents a market trend where each successive bar forms a higher low, signalling a strong and consistent upward movement.
One-Time Framing Lower (OTFL): This describes a market trend where each successive bar forms a lower high, indicating a pronounced and steady downward movement.
GOLDMAN SACHS FICC & EQUITY TRADING DESK VIEWS
EQUITY & VOL DESK BRIEFING: INCREASING RATES PRESSURE
Author: Mitch Jeter (Goldman Sachs Analyst, FICC & Equities)
Date: September 23, 2026
THE TAKE: HOT FLASH PMI & BARR COMMENTS DRIVE YIELDS TO 19-YEAR HIGHS
US equity benchmarks closed lower across the board as Treasury yields surged to multi-year highs following a hot September Flash PMI print (fastest expansion since July 2021) and rising input cost inflation across goods and services. The US 10-Year yield breached 5.10% (closing +14.7 bps to 5.1079%, a fresh post-2007 high), while the 2-Year yield hit 4.90% (highest in over 2 years).
Hawkish comments from Fed Governor Barr ("further policy adjustments are likely to be needed") combined with limited progress in US-Iran diplomatic talks pushed WTI Crude back up +2.54% to $92.85/bbl. Rates markets are now pricing a 71% probability of an October rate hike and approximately 36 bps of total additional tightening by year-end. S&P MOC imbalance finished at $5.2B to SELL.
MARKET SUMMARY & ASSET BREAKDOWN
S&P 500 (SPX): Closed at 7,706.00 (-0.75%) | MOC $5.2B to SELL | Remaining weekly straddle priced at 70 bps
Nasdaq-100 (NDX): Closed at 30,470.00 (-0.85%) | Software and mega-caps pressured by higher discount rates
Russell 2000 (RUT): Closed at 2,838.00 (-1.77%) | Small-caps bore the brunt of rate-shock selling
Dow Jones (DJI): Closed at 51,511.00 (-0.68%) | Downward drag from rate-sensitive industrial and consumer names
US 10-Year Treasury: Yield at 5.1079% (+14.7 bps) | Fresh post-2007 high; 10Y up ~25 bps in 2 weeks and ~35 bps in 1 month
WTI Crude: Price at $92.85 (+2.54%) | Bounced on stalled US-Iran talks and input cost inflation drivers
Gold: Price at $4,284.00 (-1.76%) | Pulled back under pressure from surging real yields and a firmer USD (DXY 101.11)
Bitcoin: Price at $84,270.00 (-2.31%) | Risk-off de-leveraging in tandem with equities
CBOE VIX: Closed at 15.18 (+6.83%) | Index fixed strike vols remained quiet/flat despite spot sell-off; skew bid
RATE OF CHANGE & VALUATION FRAMEWORK
Desk strategists Jason Klein, Ryan Sharkey, and Ben Snider (GIR) highlight two crucial dynamics regarding the yield shock:
Rate of Change Sensitivity (2-Sigma Threshold): Equities struggle significantly when the 10Y Treasury yield experiences a 2-standard-deviation move (~50 bps in 1 month or ~30 bps in 2 weeks). With the 10Y up ~25 bps over the last 2 weeks and ~35 bps over the past month, the market is rapidly approaching this stress threshold.
Pre-Existing Multiple Compression: The S&P 500 forward P/E multiple has quietly compressed to ~19x, showing that valuation absorption has been taking place in the background as yields rose.
INSTITUTIONAL FLOWS & DERIVATIVES COLOR
Desk Activity (-374 bps to SALE / 3/10 Rating):
Asset Managers (LOs): Net sellers of -$1.0B (supply in macro products, Healthcare, Tech, and Energy vs. light demand in Consumer Discretionary).
Hedge Funds: Net sellers of -$1.0B (supply in Communication Services, Consumer Discretionary, and Industrials vs. demand in Tech and Healthcare).
Derivatives & Volatility Dynamics:
Index Volatility & Skew: Fixed strike vols remained flat to down small across the surface despite spot weakness, but SPX and NDX skew were aggressively bid. Large institutional buyers bought SPX Dec Straddles in 4k total size (12M vega, ~$500M gamma).
Digital Assets & AI Intersection: Desk views the intersection of AI and digital assets as underappreciated; favors IBIT Calls and Call Spreads out to December for topside expression.
LatAm / EWZ Positioning: Ahead of October elections in Brazil, desk observed large IBOV call ratio trades (195k x 205k in Nov/Dec) and favors Long Delta / Short Vol structures in EWZ.
Disclaimer: The material provided is for information purposes only and should not be considered as investment advice. The views, information, or opinions expressed in the text belong solely to the author, and not to the author’s employer, organization, committee or other group or individual or company.
Past performance is not indicative of future results.
High Risk Warning: CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 69% and 73% of retail investor accounts lose money when trading CFDs with Tickmill UK Ltd and Tickmill Europe Ltd respectively. You should consider whether you understand how CFDs work and whether you can afford to take the high risk of losing your money.
Futures and Options: Trading futures and options on margin carries a high degree of risk and may result in losses exceeding your initial investment. These products are not suitable for all investors. Ensure you fully understand the risks and take appropriate care to manage your risk.
Patrick has been involved in the financial markets for well over a decade as a self-educated professional trader and money manager. Flitting between the roles of market commentator, analyst and mentor, Patrick has improved the technical skills and psychological stance of literally hundreds of traders – coaching them to become savvy market operators!